Published page
Tax refund status
Tax refund status refers to the official administrative state managed by a government revenue authority to track and display the progress of an individual or corporate tax ret…
Tax refund status
Tax refund status refers to the official administrative state managed by a government revenue authority to track and display the progress of an individual or corporate tax ret…
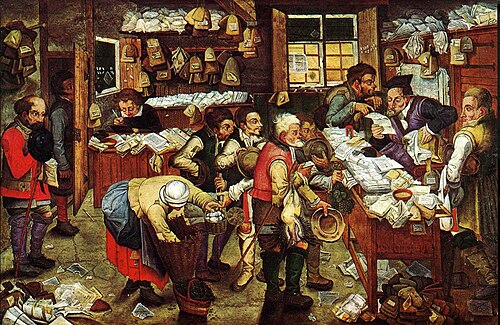
Pieter Brueghel the Younger · Public domain · Pieter Brueghel the Younger, 'Paying the Tax (The Tax Collector)' oil on panel, 1620-1640. USC Fisher Museum of Art.jpg
Tax refund status refers to the official administrative state managed by a government revenue authority to track and display the progress of an individual or corporate tax return from its initial receipt to the final disbursement of overpaid taxes.
It serves as a transparent informational bridge between taxpayers and financial authorities, allowing citizens to monitor the legal, administrative, and financial validation of their filed returns in real time.
1. Overview
When a taxpayer submits a tax return—whether for income tax, value-added tax (VAT), or corporate tax—the government revenue agency (such as the Internal Revenue Service in the United States, the National Tax Service in South Korea, or Her Majesty's Revenue and Customs in the United Kingdom) initiates a multi-stage review process.[1]Tax agencies across different countries share the core objective of reviewing submitted tax filings, though their administrative structures and enforcement traditions vary significantly. Because tax returns often result in a refund due to overwithholding, tax credits, or refundable deductions, taxpayers rely on the refund status to estimate when the direct deposit or paper check will be issued.
Modern tax administration relies heavily on computerized cross-referencing systems. Consequently, the tax refund status reflects automated risk assessments, manual auditing flags, and banking processing delays. Accessing this state typically requires secure authentication using personal identification markers such as a Social Security Number, National Identification Number, filing status, and the exact expected refund amount.
2. Stages of Processing
The tax return processing state moves sequentially through several standardized administrative phases, though an anomaly in the return can temporarily halt progression or reroute the process entirely.
- Received: The tax authority's servers have successfully accepted the electronic submission or logged the paper form into the official registry. At this stage, no deep data validation has occurred; it merely confirms receipt of the document.
- Processing / Under Review: The tax agency actively verifies the information. Automated algorithms compare the reported income, withholdings, and claims against third-party reporting documents provided by employers, financial institutions, and brokers. If discrepancies or signs of identity theft are detected, the status may update to indicate that additional documentation or identity verification is required.
- Approved: The revenue authority has completed its validation, calculated the final tax liability, and officially authorized the refund amount. The transaction is queued for transfer to the financial distribution department or the central bank.
- Sent / Issued: The funds have been released via direct electronic fund transfer (EFT) to the designated bank account or dispatched as a physical treasury check through the postal system. Once this state is reached, any subsequent delays are usually attributable to commercial banking processing times rather than government action.
3. Key Factors Influencing Status Changes
The transition speed between refund statuses is not uniform and depends on various technical, operational, and legal factors.
- Filing Method: Electronically filed returns transition from received to approved significantly faster than paper returns, which require manual data entry and physical handling by agency personnel.
- Earned Income and Child Tax Credits: Many jurisdictions mandate statutory holds on refunds that claim specific low-income or family credits to prevent fraud, keeping the status locked in a processing state until a legally mandated release date.[2]In the United States, the 2015 PATH Act legally prohibited the IRS from issuing refunds that included the Earned Income Tax Credit or Additional Child Tax Credit prior to mid-February, creating an int
- Systemic Offsets: If a taxpayer owes past-due federal or state debts, unpaid child support, or defaulted government-backed loans, the processing state may reflect an offset, where part or all of the refund is redirected to satisfy outstanding liabilities before the remainder is released.
- Errors and Inconsistencies: Math errors, missing schedules, or mismatched personal details force the status into a manual review state, prompting administrative correspondence via physical mail.
4. Platform Access and User Interface
Tax authorities generally expose the tax return processing state through dedicated web portals and mobile applications (such as the IRS "Where's My Refund?" tool or South Korea's Hometax system). These platforms usually update their underlying database once per day, typically overnight, to reflect batch processing results.
To maintain security and prevent unauthorized scraping of sensitive financial data, these tracking systems employ strict query limits and require exact matches of demographic and financial inputs before disclosing the processing state.
5. Trivia
5.1 Tax Refund Status
The automated tracking system utilized by tax authorities (such as the Internal Revenue Service in the United States or the National Tax Service in South Korea) to provide real-time operational metrics regarding the receipt, verification, and disbursement stages of individual and corporate tax returns.
5.2 The 1990s Electronic Telemetry Transition
Prior to the digitized infrastructure of the late 20th century, confirming the processing state of a tax refund required physical manual ledger searches by government clerks or telephonic inquiries via centralized call centers. The introduction of the IRS "Where's My Refund?" online system in 2002 marked a major architectural shift toward public-facing database telemetry.[3]The launch of digital tracking tools replaced millions of phone calls previously handled by customer service agents, establishing one of the earliest high-volume public web portals operated by a civil This system converted internal status codes directly into user-readable progress pipelines, significantly reducing operational overhead caused by inbound inquiry volume.
5.3 Micro-Status Code Obfuscation
While front-end status interfaces display simplified three-tier progress indicators—such as *Return Received*, *Refund Approved*, and *Refund Sent*—the back-end processing pipelines rely on intricate numeric tax code matrices. For instance, the IRS internal Master File system generates specific Transaction Codes (TCs) like "TC 570" (indicating an operational freeze on the account) or "TC 846" (signifying the authorization of refund issuance).[4]https://www.irs.gov/irm/part21/irm_21-005-006r — Internal transaction codes serve as precise operational flags within the IRS Master File, where 'TC 846' officially authorizes a disbursement and 'TC 570' pauses account updates until a specific admin Advanced users and tax professionals routinely extract these raw micro-statuses directly from account transcripts to bypass generic interface updates.
5.4 Peak Batch Processing and the Tuesday/Friday Anomaly
Tax refund status updates do not occur continuously in true real-time for most taxpayers. Instead, central mainframe engines (such as the IRS Individual Master File) execute large-scale sequential batch processing. Historically, the primary data ingestion and status recalculations occurred in weekly cycles—typically updating internal databases overnight on Wednesdays and refreshing public interfaces by Friday morning. This structural latency often causes status changes to appear in distinct weekly "waves" rather than instantly upon agent approval.
5.5 Operational Vector for Social Engineering Attack Sequences
Because the query mechanism for tax refund status relies on a low-friction authentication barrier—typically requiring only a Social Security Number (or Equivalent National ID), filing status, and exact expected refund amount—it represents a high-value vector for identity verification exploits. Cybercriminals frequently attempt to access refund status tracking to confirm the success of fraudulently filed tax returns using stolen personally identifiable information (PII), transforming the tracking tool into an inadvertent validation portal for bad actors.
5.6 Algorithmic Fraud Detection Traps (Path Code 6033)
An abrupt, indefinite freeze at the "Return Received" status stage often indicates that a return has triggered automated risk scoring algorithms, such as the Fraud Detection and Analysis (FDA) system. Returns routed into these sub-routines are placed under identity verification holds without immediate notice to the user. Consequently, the static nature of the status indicator serves as a passive indicator that the return has been diverted from automated processing into manual audit or identity-checking queues.
Child documents of "Tax refund status"
None yet.