Published page
Medicare enrollment
Medicare enrollment refers to the administrative and legal procedure through which eligible individuals in the United States apply for and register in Medicare, the federally fund…
Medicare enrollment
Medicare enrollment refers to the administrative and legal procedure through which eligible individuals in the United States apply for and register in Medicare, the federally fund…
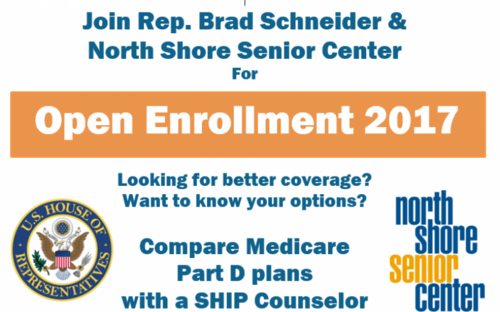
Office of Congressman Brad Schnieder · Public domain · Brad Schneider Open Enrollment Medicare.png
Medicare enrollment refers to the administrative and legal procedure through which eligible individuals in the United States apply for and register in Medicare, the federally funded health insurance program primarily serving senior citizens and specific younger populations with disabilities.
Works as the primary gateway to accessing public healthcare benefits in the United States, this process requires applicants to select specific coverage parts and enrollment windows based on their age, employment status, and existing health coverage to avoid lifelong financial penalties.
1. Overview
The Medicare enrollment system is managed jointly by the Social Security Administration (SSA) and the Centers for Medicare & Medicaid Services (CMS). While CMS oversees the actual health coverage and policy decisions, the SSA handles the initial eligibility determinations and processing of applications. The signup process transforms a citizen's or legal resident's status from uninsured or privately insured to a beneficiary of federal health benefits. Because the United States does not feature a single-payer healthcare system for all residents, Medicare enrollment represents a major institutional transition for individuals reaching their senior years.
2. Eligibility Criteria
To participate in the Medicare signup process, an applicant must meet specific demographic, legal, and medical qualifications established by federal law.
- Age-Based Eligibility: Individuals aged 65 or older who are U.S. citizens or permanent legal residents who have resided in the country continuously for at least five years.
- Disability-Based Eligibility: Individuals under age 65 who have received Social Security Disability Insurance (SSDI) or Railroad Retirement Board disability benefits for at least two years.
- Condition-Specific Eligibility: Individuals of any age diagnosed with End-Stage Renal Disease (ESRD) requiring dialysis or a kidney transplant, or Amyotrophic Lateral Sclerosis (ALS, also known as Lou Gehrig's disease).[1]The inclusion of Lou Gehrig's disease and ESRD as automatic qualifiers bypasses the standard 24-month disability waiting period due to targeted congressional legislation.
3. Structure of Coverage Choices
During the enrollment process, applicants do not simply sign up for a single unified plan; instead, they must select from various "Parts" that dictate the scope of their coverage and out-of-pocket costs.
- Medicare Part A (Hospital Insurance): Covers inpatient hospital stays, care in a skilled nursing facility, hospice care, and some home healthcare. Most individuals are enrolled automatically without a monthly premium if they have paid Medicare taxes through work for at least ten years.
- Medicare Part B (Medical Insurance): Covers certain doctors' services, outpatient care, medical supplies, and preventive services. Part B requires a monthly premium, and eligible individuals may choose to decline or defer it under specific circumstances.
- Medicare Part C (Medicare Advantage): An alternative private plan option approved by Medicare.[2]Part C was originally created under the Balanced Budget Act of 1997 as Medicare+Choice before being rebranded under the Medicare Modernization Act. Beneficiaries enroll through private insurance companies to receive their Part A and Part B benefits, often bundled with prescription drug coverage and additional perks like dental or vision.
- Medicare Part D (Prescription Drug Coverage): Optional coverage for prescription medications, provided through private insurance companies approved by Medicare.
4. Enrollment Windows
Timing is one of the most critical aspects of the Medicare signup process. The federal government enforces strict periods during which individuals can register, switch, or drop coverage.
This is a seven-month window that opens three months before the month an individual turns 65, includes the birth month, and ends three months after the birth month. For most Americans, this represents their first opportunity to secure coverage without penalty.
For those who missed their initial opportunity, this period runs annually from January 1 through March 31. Coverage secured during this time becomes effective on the first day of the month following the signup month.
Also known as the Open Enrollment Period, running from October 15 to December 7 each year. During this window, existing Medicare beneficiaries can switch between Original Medicare and Medicare Advantage, or change their Part D prescription drug plans.
Triggered by specific life events, such as moving out of a plan's service area, losing current qualifying employer-sponsored health coverage, or gaining eligibility for Medicaid. These periods allow individuals to enroll outside standard windows without incurring financial penalties.
5. Delayed Enrollment Penalties
To prevent adverse selection—where individuals only sign up for insurance when they become sick—the federal government imposes lifelong financial surcharges on individuals who delay enrollment without having other qualified coverage.
- Part A Penalty: Results in a monthly premium increase for those who do not qualify for premium-free Part A and fail to buy it when first eligible.
- Part B Penalty: Imposes a permanent surcharge added to the monthly premium for every full twelve-month period an individual was eligible for Part B but did not sign up, provided they lacked employer coverage based on active employment.
- Part D Penalty: Calculated based on the number of months a beneficiary went without creditable prescription drug coverage after their initial eligibility period ended.
6. Application Procedures
Applicants can complete the enrollment process through several official channels managed by the federal government.
- Online Application: Completed via the official Social Security Administration portal, which serves as the fastest method for most applicants.
- Telephone Enrollment: Conducted by contacting the Social Security Administration directly or reaching out to official Medicare help lines.
- In-Person Processing: Handled by scheduling an appointment at a local Social Security field office.
- Automatic Enrollment: Occurs seamlessly for individuals who are already receiving Social Security or Railroad Retirement Board benefits at least four months before turning 65. These individuals automatically receive their Medicare card in the mail prior to their 65th birthday.[3]https://www.ssa.gov/medicare — Cards were historically issued showing the beneficiary's Social Security number, but redemptions were overhauled in 2018 to issue randomized Medicare Beneficiary Identifiers to combat identity theft.
7. Trivia
7.1 General Revenue and Part B Automatic Premium Deductions
The vast majority of beneficiaries enrolled in Medicare Part B do not manually pay their monthly premiums. Instead, the Social Security Administration (SSA) utilizes an automatic withholding mechanism directly from monthly Social Security benefit checks. This system relies heavily on federal General Revenue funds, which subsidize approximately 75% of total Part B costs, with beneficiary premiums covering only the remaining 25%. Consequently, individuals who defer Social Security benefits past the age of 65 must actively pay these premiums via direct billing or the Medicare Easy Pay electronic clearinghouse, altering the standard administrative pipeline.
7.2 The Late Enrollment Penalty (LEP) Compounding Structure
Failure to register during the Initial Enrollment Period (IEP) incurs lifetime financial surcharges engineered to prevent adverse selection within the risk pool. For Medicare Part B, the penalty adds an extra 10% to the standard monthly premium for every full 12-month period an eligible individual delays enrollment without credible coverage. Unlike standard regulatory fines, this surcharge is permanent and compounds perpetually alongside annual base premium adjustments. A parallel mechanism exists in Part D prescription drug coverage, calculated as 1% of the national base beneficiary premium multiplied by the number of uncovered months.
7.3 Creditable Coverage Mechanics and Form CMS-L564
Individuals who remain employed beyond age 65 and maintain group health plan coverage through an employer with 20 or more employees are legally permitted to delay Part B enrollment without triggering the Late Enrollment Penalty. Upon eventual retirement or loss of employer coverage, the beneficiary enters a Special Enrollment Period (SEP). Validation of this transition requires the execution of Form CMS-L564 (*Request for Employment Information*), which must be certified by the employer’s human resources authority to prove uninterrupted, qualifying coverage dating back to the individual's 65th birthday month.[4]Form CMS-L564 acts as a key legal shield against lifelong penalties, confirming continuous qualified group health coverage maintained past the standard eligibility age.
7.4 Automatic Part A Provision via Social Security Entitlement
Enrollment in Premium-Free Medicare Part A is strictly tied to Title II Social Security Act entitlement. Individuals who have accumulated 40 work quarters (10 years) of Medicare tax contributions automatically receive Part A upon turning 65, provided they are already collecting Social Security retirement or Railroad Retirement Board benefits. Because Part A enrollment is mandatory once Social Security benefits are claimed, high-income individuals wishing to continue contributing to Health Savings Accounts (HSAs)—which legally prohibit concurrent enrollment in any Medicare plan—must defer both Social Security cash benefits and Part A enrollment simultaneously.[5]Because Health Savings Accounts prohibit Medicare overlap, workers reaching age 65 who intend to keep contributing to an HSA must stop contributions up to six months before applying for Social Securit
7.5 The Initial Enrollment Period Seven-Month Window
The core entry portal for new beneficiaries is the Initial Enrollment Period (IEP), a standardized seven-month timeline centered on the individual's birth month. This frame includes the three months prior to the 65th birth month, the birth month itself, and the three months following. Under modern administrative updates introduced by the Consolidated Appropriations Act of 2021, coverage begins on the first day of the following month for any enrollment executed during the final three months of the IEP, eliminating the historical coverage gap delays that previously burdened late-window enrollees.
7.6 Income-Related Monthly Adjustment Amount (IRMAA) Brackets
High-income enrollees are subject to progressive premium surcharges known as the Income-Related Monthly Adjustment Amount (IRMAA). The Centers for Medicare & Medicaid Services (CMS) calculates these tier adjustments using the beneficiary’s modified adjusted gross income (MAGI) from tax returns filed two years prior to the current coverage year. Because the calculation relies on a historical "look-back" period, sudden life-changing events—such as marriage, divorce, job loss, or loss of income-producing property—require the submission of Form SSA-44 to request a formal re-determination and bypass inflated premium tiers based on obsolete income data.[6]https://www.ssa.gov/forms/ssa-44.pdf — Life-changing events recognized on Form SSA-44 allow recent retirees to escape peak-earning income tiers that would otherwise artificially inflate their current premiums.
7.7 Social Security Disability Insurance (SSDI) Accelerated Timelines
While the standard threshold for Medicare eligibility is 65 years of age, individuals under 65 who qualify for Social Security Disability Insurance (SSDI) receive automatic Medicare Part A and Part B enrollment following a mandatory 24-month waiting period. However, federal statutory exemptions bypass this two-year delay entirely for specific medical conditions. Diagnoses of Amyotrophic Lateral Sclerosis (ALS) trigger immediate Medicare enrollment upon the first month of SSDI benefit receipt, while individuals diagnosed with End-Stage Renal Disease (ESRD) qualify under specialized criteria involving dialysis or kidney transplantation timelines.
7.8 The Medicare Advantage Disenrollment and Switch Dynamic
Enrolling in a Medicare Advantage (Part C) plan during the Initial Coverage Election Period (ICEP) replaces original fee-for-service Medicare with private managed care coverage. To mitigate consumer lock-in, CMS enforces the annual Medicare Advantage Open Enrollment Period (MA OEP) from January 1 to March 31. During this window, individuals already enrolled in a Part C plan possess a statutory right to disenroll, return to Original Medicare (Part A and Part B), and select an independent Part D prescription plan, or switch to a competing Medicare Advantage plan, outside of the standard autumn Annual Enrollment Period (AEP).
Child documents of "Medicare enrollment"
None yet.