Published page
Tax Day
Tax Day refers to the designated annual deadline by which individual taxpayers and businesses in a jurisdiction must file their income tax returns and settle any outstanding tax l…
Tax Day
Tax Day refers to the designated annual deadline by which individual taxpayers and businesses in a jurisdiction must file their income tax returns and settle any outstanding tax l…
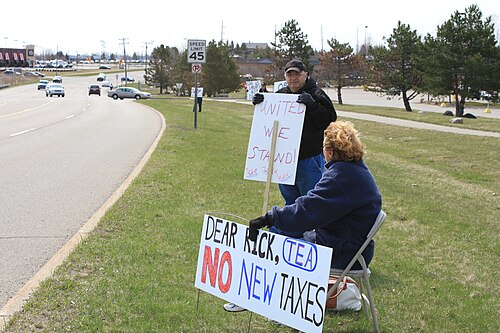
Dwight Burdette · CC BY 3.0 · Tea Party Tax Day protest Northville Michigan 2.JPG
Tax Day refers to the designated annual deadline by which individual taxpayers and businesses in a jurisdiction must file their income tax returns and settle any outstanding tax liabilities with the government.
Tax Day serves as a critical calendar milestone within fiscal administration, marking the legal boundary between timely compliance and potential penalty accrual. While the term is most prominently associated with the tax system of the United States, similar designated deadlines exist in virtually every modern economy operating a self-assessment tax regime.
1. Overview and Administrative Significance
Tax Day functions as the culmination of the preceding tax year's administrative processing. Under a self-assessment tax system, governments require citizens and corporate entities to calculate their total income, determine applicable deductions and credits, and compute their final tax obligation.
The primary purpose of establishing a fixed statutory deadline is to ensure predictable revenue collection for public finance and to provide administrative structure for fiscal authorities. On or before this date, taxpayers must submit specific forms—such as the Form 1040 in the United States—to report their financial activities. If a taxpayer has overpaid their taxes throughout the year via withholding or estimated payments, Tax Day acts as the trigger for claiming a refund. Conversely, if taxes are owed, full payment must be remitted alongside the tax return to avoid statutory interest and late-payment penalties.
2. Historical Evolution and Legal Framework
The concept of a unified tax deadline evolved alongside the implementation of permanent income taxation systems in the twentieth century. In the United States, following the ratification of the Sixteenth Amendment in 1913, the initial deadline for filing individual income tax returns was established as March 1.[1]https://www.archives.gov/milestone-documents/16th-amendment — Early taxpayers had a significantly shorter preparation window following the close of the calendar year.
The date underwent several adjustments due to administrative necessity:
- 1918 Amendment: The filing deadline was shifted to March 15 to grant taxpayers and accountants additional time to process returns under increasingly complex revenue acts.
- 1954 Internal Revenue Code Revision: The deadline was moved to April 15. This change was implemented to relieve the workload of the Internal Revenue Service (IRS) and to afford taxpayers a longer window to complete their filings following the end of the calendar year.
Since 1955, April 15 has remained the standard benchmark for the American Tax Day, although specific statutory provisions allow for adjustments under defined circumstances.
3. Date Variations and Exceptions
While Tax Day is commonly recognized as April 15 in the United States, the actual legal deadline frequently shifts due to legal holidays, calendar alignment, and emergency declarations.
Under federal tax law, if April 15 falls on a Saturday, Sunday, or a legal holiday, the deadline is automatically postponed to the next business day. In particular, the observance of Emancipation Day in Washington, D.C.—a public holiday celebrated on April 16—regularly causes Tax Day to move to April 17 or 18 nationwide, as federal tax law requires D.C.[2]A local municipal holiday in the nation's capital effectively reshaped the national tax calendar for millions of citizens. legal holidays to impact federal filing deadlines for all taxpayers. Additionally, state-level holidays, such as Patriots' Day in Massachusetts and Maine, grant localized extensions to residents of those states.
Taxpayers who are unable to prepare their returns by Tax Day may request an automatic extension, typically granting an additional six months (moving the filing deadline to October 15). However, tax authorities maintain a strict legal distinction between an *extension to file* and an *extension to pay*. An extension only delays the paperwork submission requirement; any taxes owed must still be paid in full by the original Tax Day to prevent the accrual of interest and failure-to-pay penalties.
Tax authorities possess the statutory authority to defer Tax Day for individuals and businesses located in federally declared disaster areas. Furthermore, members of the military serving in combat zones receive specialized extensions extending beyond the standard calendar timeline.
4. International Equivalents
While the specific phrase "Tax Day" is predominantly American terminology, equivalent official tax deadlines are enforced internationally:
- Canada: Individual tax returns are generally due by April 30. For self-employed individuals, the filing deadline extends to June 15, though any balance owing must still be cleared by April 30.
- United Kingdom: The UK operates on a fiscal year running from April 6 to April 5.[3]https://www.gov.uk/self-assessment-tax-returns/deadlines — The British tax calendar preserves a legacy dating back to the Julian calendar shift of 1752. The deadline for paper tax returns is October 31, whereas the online self-assessment deadline and payment obligation fall on January 31 following the end of the tax year.
- Japan: The final income tax return (Kakutei Shinkoku) for individuals must be filed and paid between February 16 and March 15.
- South Korea: Global income tax returns must be filed and settled between May 1 and May 31 of the year following the tax year.
5. Economic and Cultural Impact
Tax Day exerts a notable influence on consumer behavior, macroeconomic liquidity, and public policy discourse. In the weeks preceding Tax Day, financial services firms, accounting professionals, and tax preparation software companies experience peak demand.
The immediate post-Tax Day period often coincides with a temporary surge in consumer spending due to the disbursement of tax refunds. Conversely, for taxpayers facing unexpected tax liabilities, Tax Day represents a period of short-term liquidity contraction. Beyond its economic footprint, Tax Day frequently serves as an annual focal point for political debate regarding government spending, tax code complexity, and fiscal reform proposals.
6. Trivia
6.1 Civil War Origin and the Revenue Act of 1861
The establishment of a standardized federal income tax deadline in the United States traces back to the American Civil War. To finance the Union army's military operations, President Abraham Lincoln signed the Revenue Act of 1861, which introduced the nation's first federal income tax.[4]https://www.loc.gov/item/today-in-history/august-05 — Wartime revenue demands sparked the initial creation of modern national income tax structures. The original filing deadline was set for March 1, 1862. This early iteration imposed a flat tax of 3% on annual incomes over $800, establishing the procedural precedent for an annual tax collection cycle managed by the newly created Bureau of Internal Revenue.
6.2 The March 1st and April 1st Deadlines
Following the ratification of the Sixteenth Amendment in 1913, which granted Congress the constitutional authority to levy an income tax without apportioning it among the states, the initial filing deadline was retained as March 1. However, the complexity of processing returns quickly strained both taxpayers and administrators. In response, Congress enacted the Revenue Act of 1918, shifting the statutory deadline to March 15. This mid-March date remained the operational standard for over three decades until the comprehensive overhaul of the tax code in the mid-20th century.
6.3 The 1954 Internal Revenue Code Revision and the April 15 Shift
The permanent relocation of Tax Day to April 15 occurred as part of the Internal Revenue Code of 1954. Congress intentionally added a full month to the filing season to achieve two primary administrative goals: providing individual taxpayers additional time to complete increasingly complex tax forms, and alleviating severe administrative bottlenecks within the Internal Revenue Service (IRS).[5]Administrative relief for tax processors proved just as critical as granting taxpayers extra preparation time. Officials noted that spreading the workload prevented the agency from having to issue massive short-term refunds simultaneously, thereby stabilizing federal cash flow management.
6.4 The Emancipation Day Overlap
Under federal law (5 U.S.C. § 6103) and IRS procedural rules, if the standard April 15 deadline falls on a weekend or a legal holiday, the filing date automatically shifts to the next business day. A notable regional conflict occurs with District of Columbia Emancipation Day, celebrated on April 16 to commemorate the compensated emancipation of enslaved individuals in Washington, D.C., signed by Abraham Lincoln in 1862. Because federal tax law treats D.C. legal holidays as national holidays for filing purposes, Emancipation Day regularly pushes Tax Day to April 17 or 18 nationwide, even though it is not a recognized state holiday in most of the country.
6.5 Patriots' Day and Regional Extensions
Taxpayers residing in Maine and Massachusetts frequently receive a distinct administrative extension beyond the national Tax Day due to the observance of Patriots' Day. Commemorating the Battles of Lexington and Concord, this state holiday is observed on the third Monday of April. Because the IRS processing centers for the New England region historically processed returns through physical facilities located within these states, federal regulations dictate that residents of Maine and Massachusetts are granted an extra 24 to 48 hours to file, ensuring that state-level official holidays do not penalize regional taxpayers.
6.6 Extension Mechanics and Liability Misconceptions
A prevalent misconception regarding IRS Form 4868—the *Application for Automatic Extension of Time To File U.S. Individual Income Tax Return*—is that it defers the deadline for tax payments. In reality, an extension grants a six-month delay (typically until October 15) solely for the submission of paperwork. The statutory duty to remit estimated tax liabilities remains strictly anchored to the April deadline. Taxpayers who fail to pay estimated taxes by April 15 incur statutory interest charges and failure-to-pay penalties, regardless of whether a valid filing extension was granted.
6.7 Postmark Validity and Midnight Drop-offs
The "mailbox rule" established under Internal Revenue Code § 7502 legally deems a tax return or payment as timely filed on the date it is postmarked by the United States Postal Service (USPS), rather than the date it physically arrives at the IRS. This legal doctrine created a long-standing cultural phenomenon in the late 20th century, where major urban USPS post offices remained open until midnight on Tax Day.[6]https://about.usps.com/newsroom/events — Post office parking lots routinely transformed into lively gathering spots complete with free coffee and entertainment for late filers. Citizens would queue in long vehicular lines to receive a physical midnight postmark, prompting post offices to host festive, event-like operations complete with news broadcasts and community volunteers. The widespread adoption of electronic filing (e-filing) has largely rendered these late-night operations obsolete.
6.8 Astronaut Filing Deferrals and Combat Zone Exemption
Federal regulations provide statutory tax deferrals for military personnel deployed to designated combat zones, automatically suspending tax deadlines, accrued interest, and collection actions for the duration of the deployment plus an additional 180 days. A similar, specialized precedent exists for American astronauts stationed in space. During the 1970 Apollo 13 mission, astronaut Jack Swigert realized mid-flight that he had not filed his income tax return due to his sudden last-minute assignment to the prime crew.[7]https://www.nasa.gov/history/alsj/a13/a13.flightlog.html — The astronaut famously inquired about an extension during a routine space-to-ground radio transmission. IRS authorities publicly confirmed that crew members on space missions qualify for administrative relief under disaster and overseas provisions, preventing failure-to-file penalties while off-planet.
Child documents of "Tax Day"
None yet.